So a user wrote to us at Olyv support last month and said:
“I have been paying all my EMIs and credit card bills on time for six years. My score is 823. Why is it not 900?”
We get this question a lot, actually.
But here is the thing, 823 is already a very strong credit score. You do not need to reach a 900 score to get better credit options.
Only a very small percentage get to a 900 score. So instead of worrying about hitting the highest number possible, it is more useful to understand what your score means and what you should actually aim for.
Credit Score Range in India
Credit scores in India generally range from 300 to 900, with 900 being the highest end of the range. The four credit bureaus recognised by the RBI – CIBIL, Experian, Equifax and CRIF High Mark use this same range.
You will often hear people talk about their “CIBIL score” because CIBIL is one of the credit bureaus commonly used by lenders. But it is not the only one.
A higher score generally reflects a strong credit history like paying bills on time, keeping your card usage under control and managing loans responsibly. Things like missed payments, settled loans or write offs can work against your score.
The important thing is that you do not need to chase a 900 score. Once your score is in a strong range, what matters more is maintaining healthy credit habits over time.
You can read more about how credit bureaus are regulated by the RBI here.
Why Almost Nobody Actually Has 900
Here is something that surprises a lot of people, even if you are careful with your money and always pay on time, your score may still not reach 900.
That is because a few normal things can keep your score below the maximum:
- Applying for a new loan or card: A lender may check your credit report when you apply, which can cause a small temporary drop in your score.
- Having a shorter credit history: Someone who has been using credit for eight years may have a higher score than someone with the same good habits but only two years of history.
- Missing a payment: Even a short delay can affect your credit history, depending on how and when it is reported.
- Opening new accounts: Taking a new loan or credit card can bring down the average age of your accounts for a while.
None of this means you are doing anything wrong. It just means that 900 is the highest possible score, not a number you need to chase. A strong, consistent credit history will matter much more.
Where the Confusion Comes From
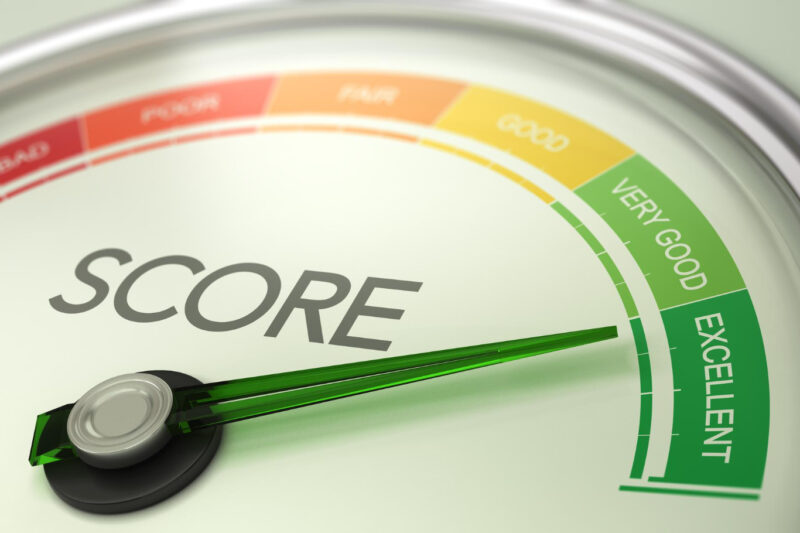
A big reason people get stuck on the number 900 is that they do not always know what their own score means. Here is a simple way to look at the different score ranges:
300–549: Poor
Your credit history may have some serious issues, missing payments or any unpaid EMIs can be some of the reasons for a low score. You may need collateral or a co-applicant in order to get a loan or credit card approval.
550–649: Fair
You may have missed a few EMIs payments here and there along with other issues for this score. You can still get a loan or a credit card but you will not get the best credit options available
650–749: Good
You have managed your credit health fairly well. You may be eligible for loans and credit cards with better credit options, this can vary from one lender to another.
750–799: Very good
A score in this range usually shows you have a strong history of paying your dues on time and managing credit responsibly. You may have access to better credit options and better loan terms.
800–900: Excellent
This is a very strong credit score range. It usually reflects a long and consistent history of paying bills and EMIs on time and managing your credit well.
Scores above 800 are less common, and scores close to 900 are even more rare. That does not mean you need to reach 900. Building a good credit history over time is far more useful than chasing a perfect score.
You can also see how credit is growing across India in recent credit growth data from the Ministry of Finance.
The “999 Score” Myth
Ever seen someone claiming a 999 credit score? In India, that is not a standard credit bureau score.
Indian credit scores generally range from 300 to 900. A 999 score usually comes from either:
- Another country’s scoring system, which may use a different range.
- An app’s own score, such as an eligibility or affordability score, which is not the same as your credit bureau score.
So if you see a 999 score online, check what type of score it actually is.
Arjun’s Score Stays Around 850
Arjun, a 34 year old IT professional in Bengaluru. He has had a credit card for nine years and a home loan for six. He checks his credit score on Olyv every couple of months, mostly out of habit.
For the past year and a half, his score has stayed between 838 and 851. It goes up a few points, drops a few, but never seems to move much higher.
Arjun has not missed a single payment in years, and he uses less than 10% of his credit limit. So why is his score not getting closer to 900?
Because a strong credit history does not guarantee a perfect score. Recent loan applications and credit checks can also affect your score, even when everything else is going well.
Arjun is not doing anything wrong. His score is simply moving within a range. And with a score around 850, he’s already in a very strong position.
Do You Actually Need a 900 Score?
Now this is the right question to ask.
In most cases, a 750 and above is already considered a strong score. It can put you in a good position when applying for loans and credit cards, although approval and terms still depend on the lender.
800 and above is excellent, but it may not give you a major advantage over a score in the 750–799 range. Some premium products may have their own requirements, but for most everyday loans and cards, the difference may be small.
900 is not something you need to chase. For most borrowers, a score in the 800s is already more than enough.
Instead of trying to reach the highest number possible, focus on keeping your score above 750 and maintaining good credit habits over time.
What Actually Moves You Closer to 900
If your score is already in good shape and you want to keep improving it, focus on these habits.
- Pay every bill and EMI on time. Your payment history is one of the biggest factors that affects your credit score.
- Keep your credit card usage below 30%. If you can keep it closer to 10%, even better.
- Keep your older accounts open. An older credit card can help show that you have managed credit responsibly over a longer period.
- Do not apply for credit too often. Apply for a new loan or card when you actually need one, rather than applying just to see if you will get approved.
- Check your credit report for mistakes. An incorrect missed payment or an account that does not belong to you could hurt your score if it goes unnoticed.
Last Updated: Sep 2026 | Reviewed By: Shree Lahari K.A., Senior Marketing Associate, Olyv